Ammonia is starting to move beyond individual vessel trials towards something more significant: the development of regional fuel supply chains. Recent developments in China, Japan and Australia suggest the next phase of adoption now depends on whether fuel producers, ports, shipowners and cargo interests can coordinate their activities around viable trading routes.
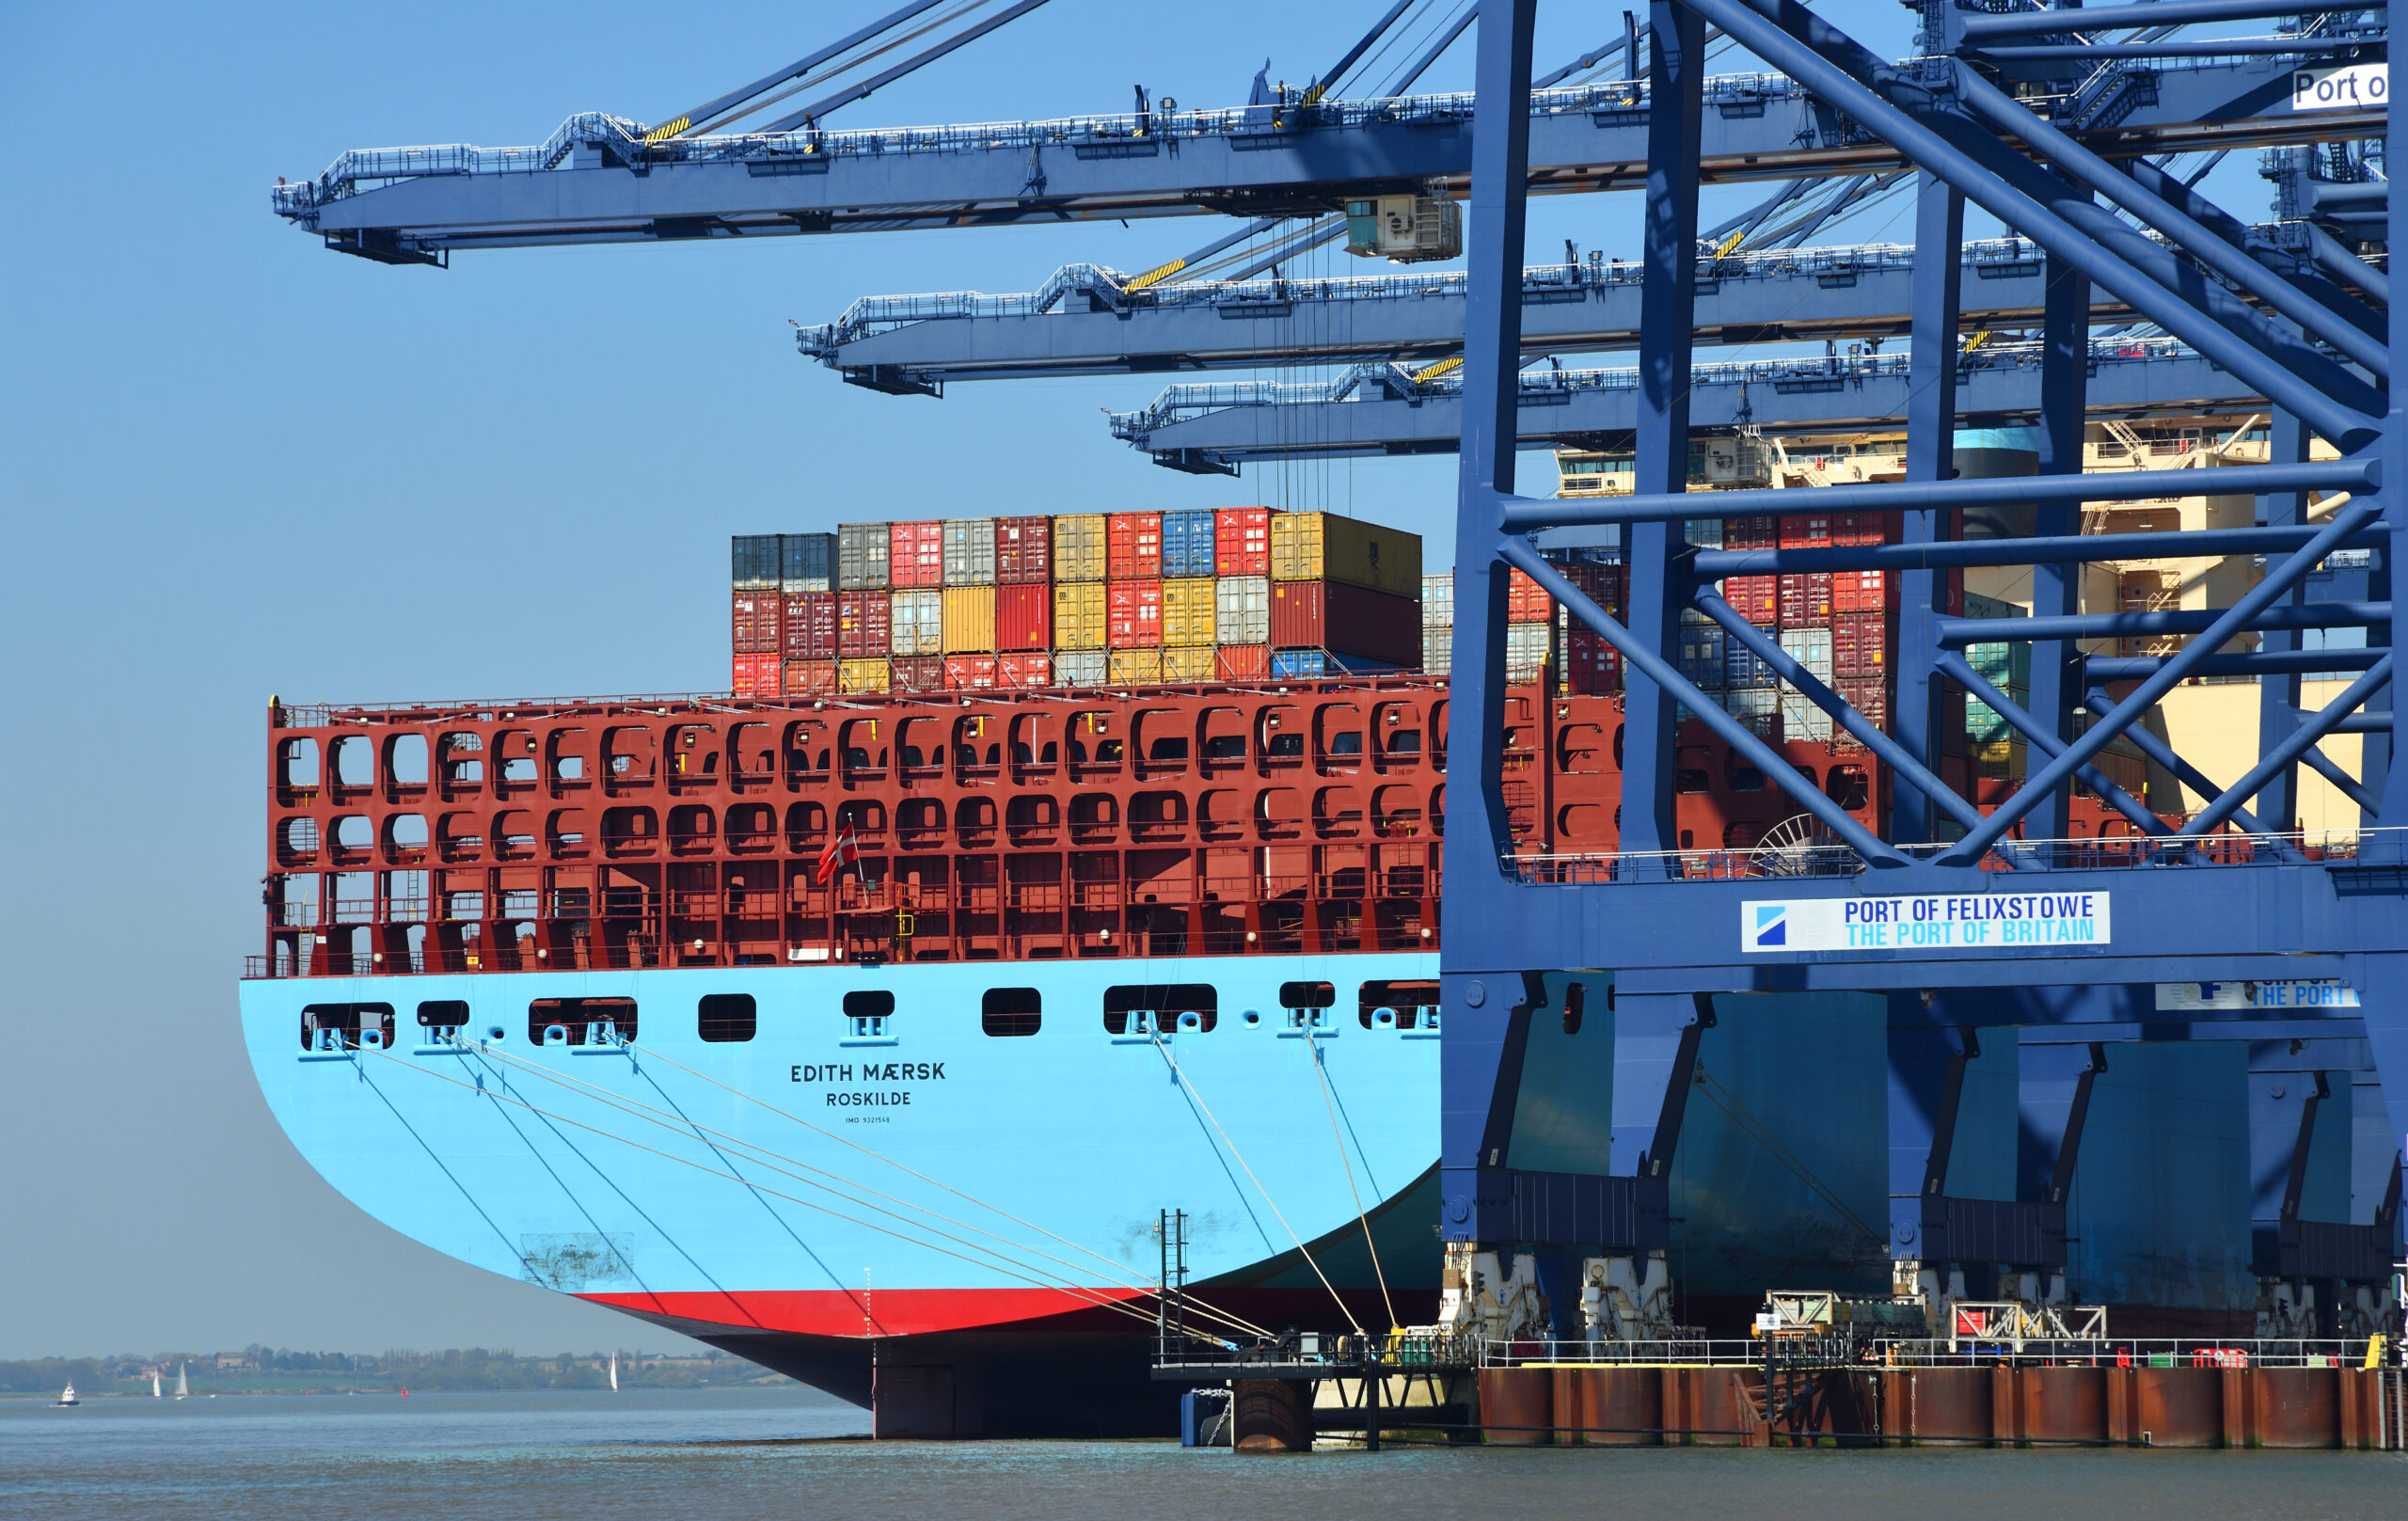
The clearest illustration of this is the Mineral Europa, the CMB.TECH vessel chartered to Fortescue. On its maiden commercial voyage, it was bunkered with certified green ammonia near Zhoushan, China, in October, before receiving a second supply at Port Hedland, Western Australia, on 2 November. It then loaded Fortescue iron ore for transport to China.
Coordinating ammonia production, transport, bunkering, vessel operation and cargo demand in two countries on a real trading voyage is a powerful message of intent and a notable show of capability. However, whether the use of ammonia can continue beyond the maiden voyage will be an interesting test of the competing needs of fuel economics and customer demand.
Three different approaches are emerging
China, Japan and Australia are approaching the challenge from different starting points, but each is addressing the same fundamental requirement: securing a dependable supply of fuel where ships need it.
China’s approach is rooted in production capacity and logistics. The green ammonia supplied to Mineral Europa originated at the Songyuan Hydrogen Energy Industrial Park in Jilin. It was transported by road to storage in Nanjing before being delivered to the vessel by the newly operational bunkering ship Sheng Hang Yong Le near Zhoushan. The 1,000-tonne operation demonstrates how industrial-scale production can be connected to marine fuel delivery, rather than relying on fuel being available at the point of production.
Japan is pursuing a coordinated, collaborative, demand-led model. A consortium involving JERA, NYK, “K” LINE and four shipbuilding companies is developing an integrated supply chain in the Chubu region, targeted for 2030. The plans encompass green ammonia procurement, terminal and loading infrastructure at Hekinan, a dedicated bunkering vessel and four ammonia-fuelled car carriers. The important distinction is that the ships and the supporting infrastructure are being planned together. This should give the investment a clearer demand base, although delivery will depend on the partners bringing the different elements into operation on schedule.
Australia’s emerging model is closely tied to its established bulk commodity trades. The Port Hedland bunkering follows an earlier ship-to-ship ammonia transfer at Dampier in 2024 and builds on plans for a Pilbara Clean Fuel Bunkering Hub. NH3 Clean Energy’s proposed WAH2 project, targeting annual production of 650,000 tonnes of blue ammonia, is intended to provide a domestic supply source, with bunkering at Port Hedland and Dampier envisaged from 2030. Itochu is involved in aggregating prospective demand, while Pilbara Ports and Oceania Marine Energy are working on the bunkering proposition. These plans remain subject to project development and investment decisions, but they indicate how fuel production could be linked directly to shipping demand.
The ships are coming
The developing supply chains are being matched by progress on the vessel side. Eastern Pacific Shipping’s Terra Clove, a 93,000 m³ very large ammonia carrier (VLAC), represents a significant step for ammonia propulsion. Built by Hyundai Heavy Industries, it is the first seagoing application of Everllence’s two-stroke ammonia dual-fuel engine. Crew preparation and safety arrangements are central to the project, with green ammonia supplied for bunkering and trials in Ulsan.
Maersk Tankers is also building a substantial presence in the ammonia-carrier market, with an order for ten 93,000 m³ VLACs capable of transporting either ammonia or LPG. Its RIPPLE project, selected for support under the EU Innovation Fund, envisages retrofitting four carriers to take ammonia as a fuel. However, Maersk Tankers has made it clear that proceeding will depend on customers demonstrating that they are prepared to support the additional investment.
Kawasaki’s delivery of Aurora Borealis illustrates the growing scale of investment in ammonia-capable shipping. The 86,700 m³ vessel is the fourteenth of Kawasaki’s latest LPG-fuelled LPG/ammonia carrier design. These ships can carry LPG and ammonia, including both simultaneously, and are currently powered by LPG rather than ammonia. However, the Aurora Borealis has also received ClassNK concept design approval for future conversion to ammonia propulsion should the commercial case develop.
Meanwhile, MOL’s plans, in partnership with CMB.TECH, for three ammonia-capable Capesize bulkers point to the potential for the Pilbara–Asia trade to become a significant source of future demand.
Are regional corridors the answer?
The Australia–Asia iron ore route has several advantages as an early market for ammonia. It is a substantial, established trade with concentrated cargo flows, repeat voyages and a relatively small number of major ports and commercial participants. These characteristics make it easier to coordinate fuel supply, bunkering infrastructure and vessel deployment in a fragmented global market.
The Mineral Europa operations provide an early and important demonstration of what this could look like, but two successful bunkerings do not constitute a commercially sustainable corridor. The availability and price of ammonia, the reliability of supply, the cost of dual-fuel vessels, safety procedures and the emissions performance of the fuel all need to be addressed.
China’s production and logistics capabilities, Japan’s coordinated demand model and Australia’s resource-led approach are complementary, but their long-term value will depend on whether standards, infrastructure and commercial arrangements can connect them.
However, concentrating investment around established trades does allow the industry to build experience, develop operating standards and establish dependable demand before extending supply networks more widely.
The developments in China, Japan and Australia suggest that the maritime industry is starting to organise the fuel supply chains it will need. The Pilbara–Asia corridor may provide one of the most important early tests of whether it can work commercially.